Vietnam’s economy to end on a high note at the end of 2022
FDI disbursed in the first 11 months surged 15.1 percent YoY to USD19.7 billion, the highest growth in five years
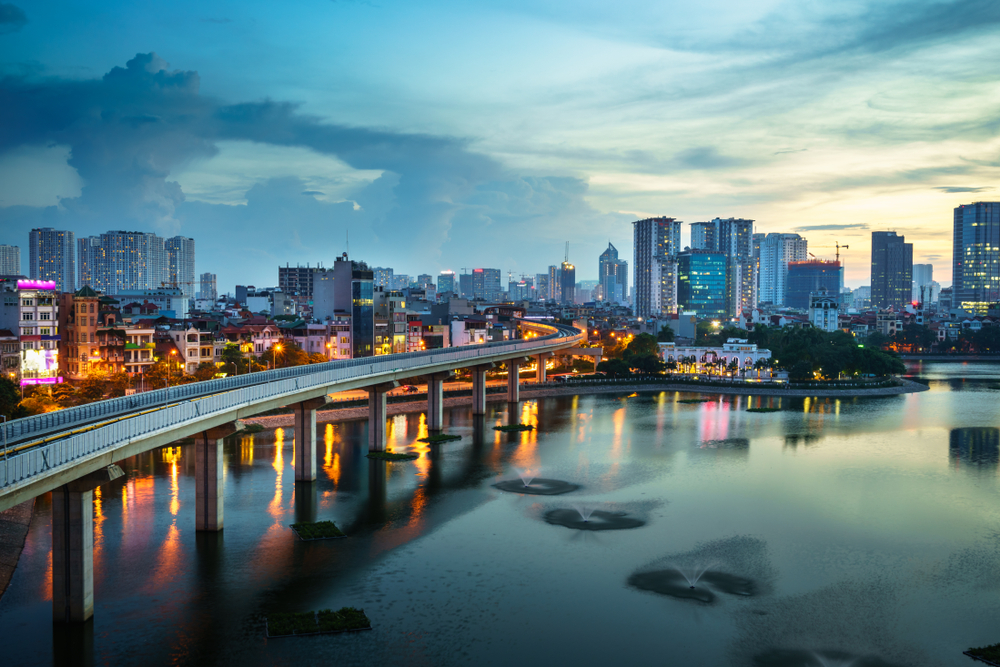
Vietnam’s economy is expected to reach eight percent this year, which can be attributed to continuous expansion and surges in trade surplus and foreign investment, according to VnExpress. World Bank and HSBC estimate the country’s growth to be 7.2 percent and 7.6 percent, respectively.
It grew by 8.8 percent from January to September—the highest increase since 2011. This is on the back of a 13.7 percent expansion in Q3.
Moreover, FDI disbursed in the first 11 months surged 15.1 percent YoY to USD19.7 billion, the highest growth in five years. The country welcomed investors from 107 countries and territories. Singapore dominated this list with USD5.8 billion, accounting for 23 percent of total investments.
More: Vietnam sees 11.5% increase in FDI inflows
A total of 14 percent of newly registered capital came from Ho Chi Minh City, followed by Binh Duong Province and Quang Ninh Province.
At the beginning of the year, Vietnam’s real estate market skyrocketed when speculators flocked to Hanoi, Ho Chi Minh City, Binh Duong, Dong Nai to trade land and homes, propelling profits to double-digit growth within months.
According to Savills Vietnam, Ho Chi Minh City’s apartment absorption rate in Q3 was 15 percent, the lowest since 2019, while unsold inventories increased to a four-year high of 66 percent of primary supply.
Nguyen Thanh Nghi, the minister of construction, noted that issues in the real estate market would continue for as long as the supply and demand are not balanced.
Meanwhile, Vietnam Briefing pointed out several factors that keep the country’s economy on fast track despite oncoming headwinds. One of these being the nation’s investment in infrastructure.
Vietnam invests approximately six percent of its GDP in its infrastructure, which is significantly high in a regional context.
These include the 1,800 km HCMC–Hanoi highway; the Long Thanh International Airport; metro projects in Hanoi and HCMC, as well as thermal and waste-to-energy power plants.
The government is also determined to change labour dependency and has offered incentives for high-tech businesses. Moreover, the sale of used equipment that is more than a decade old has been prohibited.
The Property Report editors wrote this article. For more information, email: [email protected].
Recommended
Is China’s housing market finally turning a corner?
Shanghai’s property revival raises hopes, but falling prices elsewhere point to a long recovery
Opportunity or trap? What Washington’s high-tech hub outside Manila means for Philippine property
The New Clark City Economic Security Zone promises billions in investment, but at what cost to Philippine sovereignty?
What Japan’s policy rate hike means for its property market
After decades of near-free borrowing, the country's policy rate is starting to reshape the calculations behind property investment
A conversation with the head of Vietnam’s Green Building Council on the cost of doing nothing
The VGBC’s Douglas Snyder argues that the real cost developers should fear isn’t building green. It’s failing to do so